8 lectures · On site / Online · Hebrew / Russian / English
Startup Education
Lectures for startup founders and teams
Alexander Slutsker, Business consultant, entrepreneur and founder of Mobius Business Solutions
From economics to fundraising to Agile, everything a startup team needs to understand in order to build, grow, and attract investment.
+972 055-248-6151. Better on WhatsApp: I am in meetings most of the day and answer as soon as I am free. Other ways to reach me
I have worked with
- Google for Startups
- House of Business, Sderot Municipality
- Microsoft Reactor
- GameReady
- Eclipse Capital
- SderoTech
- IUCEL
- Resilience & Health Innovation Hub
- International Resilience Institute of Sderot


- Google for Startups
- House of Business, Sderot Municipality
- Microsoft Reactor
- GameReady
- Eclipse Capital
- SderoTech
- IUCEL
- Resilience & Health Innovation Hub
- International Resilience Institute of Sderot
How booking works
- 1
Get in touch
Send a WhatsApp message or use the form, with the date, the audience and the setting.
- 2
A short planning call
On the call the content and examples are matched to your audience and goals, and we choose the format and the language together.
- 3
The lecture is delivered
On site or online, questions from the room included.
Photos from lectures and certificates
Lectures in this topic
Open a lecture to see what your audience takes away and who it suits.
What Sets Startups Apart from Small Businesses
Startup route or regular business, and how to tell where your own idea belongsStartup founders, New entrepreneurs
Entrepreneurship and a startup are not the same thing, and anyone who mixes them up builds the business on the wrong model. Some people set up a service business and chase investors as if it were a startup. Others hold an idea with real growth potential and run it like a corner shop. This lecture breaks down what makes a startup different, the drive for growth, the appetite for risk and the focus on innovation, and shows how the two paths really differ in strategy, funding and market positioning. You leave with an answer to which path your idea belongs on, and why.
What your audience takes away
- Tell whether your idea is built for the startup path or for a regular business.
- Explain to a bank, a partner or an investor what kind of capital you need and why.
- Choose an operating model that fits the pace of growth you are aiming for.
- Check how much risk you are willing to take before committing to a long road.
- Look at your market positioning through an investor's eyes, and adjust it.
Who it suits and common questions
Who this lecture is for
Built for accelerator and incubator programme managers assembling a founder cohort, municipal young adult centres and business departments running entrepreneurship evenings, university and college entrepreneurship centres, and small and medium business owners' forums where members keep asking whether their business could be a startup. It also suits welfare and human resources coordinators who want an enrichment session with a real decision inside it. Mixed rooms are welcome, because the comparison gives both the product founder and the bakery owner something to act on.
Questions about this lecture
- I already run a profitable small business. Can it become a startup, or would I need to start something new?
- Both routes exist and the lecture treats it as a decision rather than an upgrade. We look at what would have to change in the model itself, not just in ambition, and at which existing businesses genuinely carry a scalable core versus which are healthy exactly as they are. Owners usually leave with a clearer answer than the one they came in with.
- Is a services or consulting business ever a startup, or does it require a product?
- This comes up in almost every room. The lecture works through what makes revenue repeatable without adding people in proportion, which is the real test, and shows where a services business can carry a product inside it. Participants who conclude their business is not a startup are not being told they failed, they are being told to stop applying rules written for a different game.
- If a venture turns out not to be a startup, what funding routes stay open to it?
- The comparison covers this directly, because the mismatch between funding type and business type is where a lot of owners get stuck. We separate capital that expects an exit from capital that expects repayment, and look at what each one asks of the owner in exchange. Nobody leaves thinking venture money is the only serious money.
- How does the lecture handle the failure rate that entrepreneurship content always leads with?
- It refuses to use it as a scare statistic. Raising anxiety without giving anyone a decision framework is the standard move in this space and it helps nobody. Instead the session treats risk as something you size and bound before you commit, so the room ends with a way to test an idea cheaply rather than with a vague sense of dread.
- How much ownership does the startup path usually cost a founder?
- Rather than quoting figures that shift with the market, the lecture explains the mechanism, why outside investors need a meaningful share, how each round changes the founder's position, and what that means in daily practice for who decides what. Participants get the logic, so they can read any specific offer they later receive instead of memorising a benchmark.
Understanding Startup Economics and Unit Economics
What a new customer costs, what they return over time, and how to measure itStartup founders, Tech entrepreneurs
The room goes quiet. An investor has just asked what a new customer costs you and how much that customer brings back over time. The team tracks numbers that are pleasant to look at, not the numbers that drive decisions. This lecture goes back to the basics of startup economics, revenue models, cost structures and the metrics that make up unit economics, and shows how to measure them and improve them so that growth can last. Every metric is explained before it is used, so people in product, marketing and operations stop guessing what is being said around them in the meeting.
What your audience takes away
- Work out what a new customer costs and what that customer brings back.
- Know when to raise the marketing budget and when to stop it.
- Spot vanity metrics and replace them with metrics that drive a decision.
- Answer an investor's unit economics question without stumbling.
- Talk to product and marketing in the same financial language.
Who it suits and common questions
Who this lecture is for
Written for accelerator and incubator programme managers who need a numbers session inside a founder cohort, and for startup chief executives booking an internal session for people who never studied finance, meaning product, marketing, community and operations staff. Growth and marketing leads whose teams optimise channels without a payback rule get direct value, as do angel and investor clubs preparing members and portfolio founders to speak one metric language. Outsourced finance directors and advisory firms book it when a client's model reports revenue but never cost per customer.
Questions about this lecture
- Does this work for a business that is not subscription based, such as a marketplace, hardware or a services company?
- Yes, and that gap is deliberate. Almost everything published on this subject assumes a subscription product, which leaves marketplaces, hardware, services and long-cycle business-to-business companies guessing. The lecture works from the underlying question, what one customer costs and what one customer returns, then shows how that question changes shape in each of those models.
- Which costs belong inside customer acquisition cost, and does founder salary count?
- This is the honest numbers problem and the lecture spends real time on it. Models get flattering when overhead, founder time and the cost of serving a customer quietly move to whichever line looks better. The session sets out a consistent way to draw those boundaries, and shows what happens to the picture when a team draws them differently.
- What do you do when the company is too early to have real retention data?
- Most rooms are in exactly that state. The lecture covers what an early company can measure honestly, how to build an estimate that is labelled as an estimate rather than dressed up as a fact, and which early signals genuinely tell you something. It also names the point at which you have enough data to stop guessing.
- Will product and marketing people follow it without a finance background?
- That is who it is written for. The terms arrive as acronyms, LTV, CAC, churn, ARPU, and half a room usually guesses at them in silence. The session gives everyone the same plain definitions first, so a board update or an investor conversation stops sounding like noise to the people who are actually driving the numbers.
- How does this connect to what investors and lenders here actually ask?
- Directly. Weak metric literacy has a financing cost, because the people deciding whether to back a company increasingly examine efficiency per customer rather than headline growth. The lecture frames each metric the way it gets asked about in a real meeting, so founders recognise the question when it arrives rather than translating it on the spot.
Fundraising Stages and Investor Expectations
From seed to Series A, what each stage expects to see from youStartup founders
A founder walks into a meeting with a Series A story and early stage evidence, then wonders why nothing follows. This lecture walks you through the fundraising journey from seed to Series A: what an investor expects to see at each stage, how the decision looks from the other side of the table, and what really happens in due diligence after the yes. You get a practical explanation of what to present, when to approach investors and what needs to be in order before you start. The content is for enrichment and education only and is not tax, legal, investment or insurance advice. Before a binding legal, tax or investment decision, consult a qualified professional.
What your audience takes away
- Identify the funding stage you are really at, not the one that feels comfortable.
- Match what you present to what investors expect at that stage.
- Prepare for due diligence before it starts, not while it is under way.
- Run a pipeline of investor meetings instead of chasing a single investor.
- Understand what an investor needs from the deal to say yes.
Who it suits and common questions
Who this lecture is for
Aimed at accelerator and incubator programme managers preparing a cohort for demo day and first investor meetings, founder communities and angel clubs running pre-round preparation, and university and college entrepreneurship centres that need a fundraising module inside an existing course. Corporate innovation and venture arms book it to brief internal teams on how the startups they evaluate get financed. Outsourced finance directors and advisory firms with startup clients use it as the neutral teaching session their own published explainers were never designed to be.
Questions about this lecture
- Does the session cover pre-seed and Series A, or only the seed round?
- It covers the progression, which is the part most published guidance skips. Almost everything available locally stops at seed, so founders learn one round in isolation and then meet the next one unprepared. The lecture treats each stage as a set of expectations the previous stage was supposed to produce evidence for.
- Do you address grants and other non-dilutive funding alongside equity?
- Yes, and it is one of the clearest gaps in what founders are usually told. Guides written by people who sell equity-related services tend to present equity as the only route. The session puts dilutive and non-dilutive capital side by side and asks what each one costs the founder, in ownership, in reporting and in the freedom to change direction.
- Will founders learn what is actually inside a term sheet?
- Yes. Term sheets get named in most content and opened in almost none. The lecture goes through the clauses that decide what a founder is left holding, valuation, the option pool and where it comes from, liquidation preference, pro rata rights, and board composition, in plain language rather than legal phrasing.
- What traction evidence does each stage expect, and how do founders know they are raising too early?
- This is the spine of the session. Each stage is framed by the proof it expects rather than by a target amount, so founders can look at their own evidence and place themselves honestly. Raising too early burns the introductions you cannot get back, so the lecture is equally clear about when to wait.
- Is this relevant to founders outside technology, or is it venture capital specific?
- Both audiences get value, but they get different things. Venture logic is explained properly, including why a fund's own economics make it reject good businesses that simply do not fit its model. Founders outside technology leave understanding why that door is closed to them and which financing doors are open instead, which is a more useful outcome than a rejection they never understood.
Agile and Lean Methodologies in Practice
Agile and Lean in a small team, from the principles behind the ceremonies to the feedback loopStartup founders, Development teams
You hold a stand-up every morning, close a sprint and sit down for a retro, and the results stay exactly as they were. That is what it looks like when a team adopts the rituals without the principles behind them. This lecture takes Agile and Lean back to what they really are, ways to shorten the distance between a decision and real feedback from the market. It covers fast iteration, building customer feedback into everyday work, and the savings that come from no longer building things nobody asked for. Most of what is sold on the Israeli market is built for a large organisation with dedicated roles. The angle here is a small team that needs to work differently tomorrow morning.
What your audience takes away
- Spot when the ceremonies are running on empty, and drop what is not needed.
- Close a feedback loop with a customer before building the next feature.
- Stop building what nobody asked for, and cut costs along the way.
- Choose Scrum, Kanban or no framework at all, depending on the situation.
- Run a short iteration in a small team without dedicated roles.
Who it suits and common questions
Who this lecture is for
Built for startup founders and small product teams with no Scrum Master, no Product Owner and no project management office, the audience the local Agile training market skips almost entirely. It also serves research and development leads who want the principles back without another certification track, human resources, learning and organisational development managers programming a team day, and non-technical functions such as sales, service, finance and marketing that were told to work in an agile way and never had it translated into their own work.
Questions about this lecture
- Does this cover Lean startup and MVP thinking, or only Scrum, Kanban and ceremonies?
- Lean gets equal weight, which is unusual here. Most local training treats Lean either as manufacturing-style process improvement or as a footnote inside a strategy day for executives. The session gives build, measure and learn, minimum viable products and validated learning their own space, because deciding what to build matters more than the cadence you build it in.
- Does it work for a small startup team with no Scrum Master and no Product Owner?
- That is the intended room. Nearly all available training assumes an organisation that already has those roles, plus a backlog structure and a project office to support them, which leaves a five-person team nothing usable. Everything here is scaled to a team where one person often wears three hats.
- Do you cover when Agile is the wrong choice and when to drop a ceremony?
- Yes, and it is one of the reasons the session exists. Every vendor sells its own framework as the answer, so nobody teaches the limits. Teams leave able to say out loud that a particular ritual has stopped producing anything, and to retire it deliberately instead of attending it resentfully.
- Is there anything for managers, given that most Agile adoptions stall at the management layer?
- There is, because teams changing while their managers do not is the standard failure pattern. The lecture covers what managers have to give up, mainly the habit of being the decision point for everything, and what changes in how progress gets reported upward. Without that part, teams do the new rituals and the old dynamics stay exactly where they were.
- How does this differ from the Scrum Master and Product Owner courses our people already took?
- Those courses teach a framework and issue a credential. This one goes at the principles underneath, and specifically at the gap between running the practices correctly and getting a better outcome. It is the conversation for teams who did the certification, followed the process, and still cannot point to what improved.
Finding Product-Market Fit: Strategies and Metrics
From proving the need is real to the choice between narrowing, persevering and pivotingStartup founders
You have been building features for months, and nobody in the room can say what evidence would convince them they are wrong. There are anecdotes, but no measurement. This lecture covers how to identify and validate the real needs of your target market, the metrics that define product-market fit, and the iterations that bring the product closer to a winning fit. It also covers the part almost nobody touches, what to do when the fit is only partial: when to narrow the segment, when to pivot and when to persist. In Israel it is easy to get meetings through personal connections, so the lecture also looks at polite feedback that sounds like validation and is not.
What your audience takes away
- Define in advance what evidence will prove the need is real, before building a feature.
- Measure product market fit with metrics, not gut feeling.
- Recognise when a polite customer gives you feedback you cannot rely on.
- Decide between a pivot, a narrower segment and staying the course, using clear criteria.
- Run customer interviews that end in a decision, not only a good feeling.
Who it suits and common questions
Who this lecture is for
For university entrepreneurship clubs and business school venture programmes running founder evenings, accelerator and pre-accelerator programme managers who need a structured validation session inside a cohort curriculum, and innovation and community managers at coworking hubs and municipal business houses booking founder track content. Consulting firms hosting founder meetups book it as the outside voice in the room. Corporate innovation leads and product groups inside established companies use it before committing development budget to a second product line.
Questions about this lecture
- Which metrics do you teach for measuring fit, and do they differ for business-to-business and consumer companies?
- They differ substantially, and the lecture keeps them apart. A consumer product and an enterprise product produce completely different signals, on completely different timescales, and applying one set to the other is how teams convince themselves too early. Participants leave knowing which handful of measures their own model should be watching.
- We already have paying customers. Does this still apply, or is it only for pre-revenue teams?
- It applies most sharply to companies with revenue, because early revenue is the easiest thing to mistake for fit. A few enterprise pilots from warm contacts can look identical to a market, right up until spending scales against that signal. The session gives paying companies a way to test whether the demand is real or borrowed.
- How do you handle the local reality where early customers arrive through personal connections and give biased feedback?
- Head on, because it is the specific trap here. A well-connected ecosystem makes customer conversations easy to arrange and much harder to trust, since people who like you answer generously. The lecture covers how to structure those conversations so the polite answer becomes visibly different from the real one, and which signals to weight instead of stated enthusiasm.
- Do you cover fit for a new product line inside an established company rather than a new startup?
- Yes, and it is barely addressed anywhere else. A second product inside a company with existing customers, an existing brand and existing distribution has advantages that mask weak signals, and internal politics that punish honest negative findings. The session covers how to validate under those conditions without the first product's success doing the arguing.
- How do you talk about pivoting without demoralising the founders in the room?
- By treating it as an evidence-based decision rather than an admission of failure. The session gives criteria for narrowing a segment, for persevering, and for changing direction, which turns a loaded emotional question into a normal management one. Founders who arrive suspecting the answer usually leave relieved that there is a method for it.
Building a Founding Team and Structuring Equity
The equity split conversation, how you run it and how it produces the numbersStartup founders, Early employees
The equity split gets settled in the first excited week. Two years later the contributions no longer look the same, and nobody wants to reopen it. This lecture covers building a diverse, high-performing founding team, splitting equity, incentives and the legal considerations that keep partners' interests aligned. Most of what is written in Hebrew on the subject explains what the document should say. Here the emphasis is on the conversation itself: how friends talk about contribution and value, what to decide before you walk into a lawyer's office, and how to keep working together when the numbers are not equal. The content is for enrichment and education only and is not tax, legal, investment or insurance advice. Before a binding legal, tax or investment decision, consult a qualified professional.
What your audience takes away
- Hold the equity split conversation without burning the partnership.
- Define roles and decision authority before the first serious disagreement.
- Walk into a lawyer's office with decisions made, not a list of questions.
- Build incentives for the first employees that actually keep them with the company over time.
- Know what happens to ownership when a co-founder leaves early on.
Who it suits and common questions
Who this lecture is for
Written for accelerator and incubator programme managers who currently outsource this slot to a law firm, university entrepreneurship clubs where co-founder teams are forming in the room, and founder communities and meetup organisers who watch co-founder conflict repeat itself. Startup people leads and finance leads preparing a first employee option plan book the version aimed at employees rather than founders. Municipal and regional business houses running founder cohorts get the case that comes up constantly, two or three partners starting a venture together.
Questions about this lecture
- Do you give an actual method for deciding the percentages, or only explain what the agreement should contain?
- A method, and that is the whole point of the session. Every available explainer describes the contents of a founders agreement, which is the part a lawyer will handle anyway. What founders are genuinely stuck on is the conversation that produces the numbers, so the lecture works through the inputs: past contribution, future commitment, capital, risk carried, and how to weigh them together.
- Do you cover vesting, cliff and reverse vesting, and what happens when a co-founder leaves in the first year?
- Yes, and they are treated as the centre of the topic rather than a technical appendix. These mechanisms decide who keeps what when someone leaves, which is precisely the scenario founders never plan for. The session also covers reverse vesting on shares already issued, which is the awkward case teams discover only when they need it.
- Can this be run for a team that already split the equity and now needs to change it?
- Yes, and a large share of real demand looks exactly like that. Renegotiating an existing split is harder than setting one, because somebody has to give something up in front of the others. The lecture covers how to open that conversation, what makes it survivable, and which mechanisms let a team correct course without anyone feeling ambushed.
- Is this a substitute for a lawyer, or preparation for meeting one?
- Preparation, and the distinction is stated openly. Most published material on this subject is written to make founders feel they cannot take a step without counsel, which leaves them paying for a template they still do not understand. The session tells founders which decisions are theirs to make and which genuinely need professional drafting, so the meeting is shorter and far more useful.
- Do you cover employee options and how the pool dilutes founders when investors come in?
- Yes, and putting both halves in one session is deliberate. Founder shares and employee options are usually taught by entirely different specialists, so nobody sees the whole cap table at once. The lecture connects them, including where the option pool comes from in a funding round and what it costs the founders in practice.
From First Product to Growing Company: Scaling the Right Way
What breaks as the company grows, and how you build processes in real timeStartup founders
Once the company grows, what worked when you were a small group stops working. The founders become the bottleneck for every decision, because nothing is written down anywhere. This lecture is about scaling itself: balancing the pace of growth with operational efficiency, and expanding the product, the team and the market reach. The part almost nobody touches is what is actually worth keeping, because the speed and improvisation that got the company this far are an asset at one stage and a burden at the next. The question of when to add a professional management layer above the original team is also asked out loud.
What your audience takes away
- Spot what is about to break in a growing company before it breaks in public.
- Choose between growth and profitability using criteria, not the mood of the last meeting.
- Take the founders out of the bottleneck on every decision.
- Decide what to keep from the startup days and what to stop doing.
Who it suits and common questions
Who this lecture is for
Aimed at founders and chief executives of post-MVP companies approaching the move to a professional management layer, and at human resources, learning and organisational development managers inside technology companies that grew fast and now feel the process gap. Executive forums and management teams book it for an offsite, and venture fund and accelerator platform teams run it across a portfolio of founders crossing from build to scale. Established non-technology companies launching their first digital product hit the same wall and belong in the room too.
Questions about this lecture
- Is this about growth mindset or about concrete operating mechanics such as processes, metrics and organisational design?
- Mechanics. The corporate lecture market treats growth as an inspiration topic, which is why executives keep booking motivating sessions and returning to the same bottlenecks the following week. This one deals with where decisions actually sit, which of them have to be written down, what gets measured across product, sales and finance, and how the structure changes as headcount does.
- Do you cover the growth versus profitability decision, and do you give criteria for choosing?
- Yes, with criteria rather than a preference. Most commentary names this as the big choice and then leaves the executive team to decide by instinct, which in practice means echoing whichever one the last funding conversation favoured. The lecture sets out what each path demands of the company operationally, so the decision is made once, on purpose, and communicated the same way to everyone.
- How do you address the improvisation culture that works brilliantly in a small team and breaks at scale?
- Directly, and it is usually the part of the room that goes quiet. Improvisation is a genuine competitive advantage early and a genuine liability later, and nobody wants to be the person who names it. The session gives management a shared, non-accusatory way to talk about which improvisations to protect and which have already turned into risk.
- Do you cover what a company should deliberately stop doing as it scales, not only what to add?
- Yes, and it is the half that gets skipped everywhere else. Every vendor sells either more process or more spirit, so founders are left afraid that structure will kill whatever made them work. The lecture puts the trade-off on the table honestly, including what to protect deliberately and what to retire without ceremony.
- Do you cover hiring the first professional managers over the original team?
- Yes, including the resentment nobody plans for. Bringing experienced managers in above the people who built the thing is one of the most predictable sources of damage in a scaling company, and it is almost never discussed out loud before it happens. The session covers how to sequence it, how to explain it, and what to give the original team so the move does not read as a demotion.
Startup Legal and Financial Basics
Contracts, ownership of work and reports in one session, and what needs a professionalStartup founders, Early employees
A customer contract, a confidentiality agreement, a freelance agreement. Founders sign all of them without really knowing how to read them, and the cost shows up in due diligence, when there is no time left to fix anything. This lecture brings together two worlds that on the Israeli market almost never meet. The legal side: legal entities, contracts and intellectual property rights. The financial side: reading financial statements, accounting, tax considerations and risk management. The goal is simple: to know which decisions you can make on your own and which need a lawyer or an accountant. The content is for enrichment and education only and is not tax, legal, investment or insurance advice. Before a binding legal, tax or investment decision, consult a qualified professional.
What your audience takes away
- Read a customer contract and pinpoint the clauses that create exposure.
- Make sure the intellectual property rights are actually held by the company.
- Tell profit on the report apart from cash in the bank.
- Know which decisions need a lawyer and which you can make yourself.
- Arrive at due diligence with your house in order, not caught by surprise.
Who it suits and common questions
Who this lecture is for
Built for accelerator and incubator programme managers filling the legal and financial slot in a cohort curriculum, regional small business agency branches and municipal business development centres running early-stage entrepreneur courses, and university and college entrepreneurship programmes and student venture clubs. Coworking spaces and founder communities that want practical rather than inspirational content book it directly. Social venture and nonprofit accelerators, where founders arrive with no commercial background at all, get a version that assumes nothing. Startup people and finance leads book it for early employees.
Questions about this lecture
- Does this cover both the legal and the financial side, or do we need two separate speakers?
- One session, both halves, which is the reason it exists. Law firms publish on the legal side, finance providers publish on the financial side, and a founder is left assembling two incomplete pictures. The lecture connects them at the points where they actually meet, structure and liability, contracts and revenue recognition, ownership of work and company value.
- Is it aimed at pre-revenue startups, or is it the same material as a general small business finance workshop?
- It is written for the startup stage specifically. General small business finance content is built around established operations with steady customers, and its worked examples are clinics and studios. None of that speaks to a pre-revenue venture with investors, a cap table and development spend, so this session starts from that reality instead.
- What does the session say founders can handle themselves versus what genuinely requires a lawyer or an accountant?
- It draws that line explicitly, which almost nothing else does. Content written to sell professional services has an obvious incentive to leave founders feeling helpless. Here founders learn which decisions are theirs, which documents they can read unaided, and exactly where professional drafting or professional judgement is worth paying for.
- Do you cover ownership of work created by freelancers, co-founders and previous employers, or only registration?
- Assignment gets the attention, because that is the failure mode that actually derails deals. Most published material treats intellectual property as registration and patents, while the thing that surfaces in due diligence is a contractor who was never asked to assign what they built. The session covers when that assignment has to happen and what it looks like when it was missed.
- How is this different from the subsidised entrepreneurship courses our participants can already take?
- Those courses are broad and general, covering business planning for anyone starting anything. This session is narrow and sequenced for the startup path, giving an order of operations, what to settle before incorporating, before the first hire, before the first customer contract and before the first investor conversation. It complements a general course rather than repeating it.
Why I built these lectures
I've seen startups fail not because of a bad product, but because founders didn't understand the rules of the game they were playing. Fundraising, unit economics, team equity. These aren't abstract concepts, they're survival skills. I built these sessions so founders get the literacy they need before sitting across from an investor, not after.
Who delivers the lectures
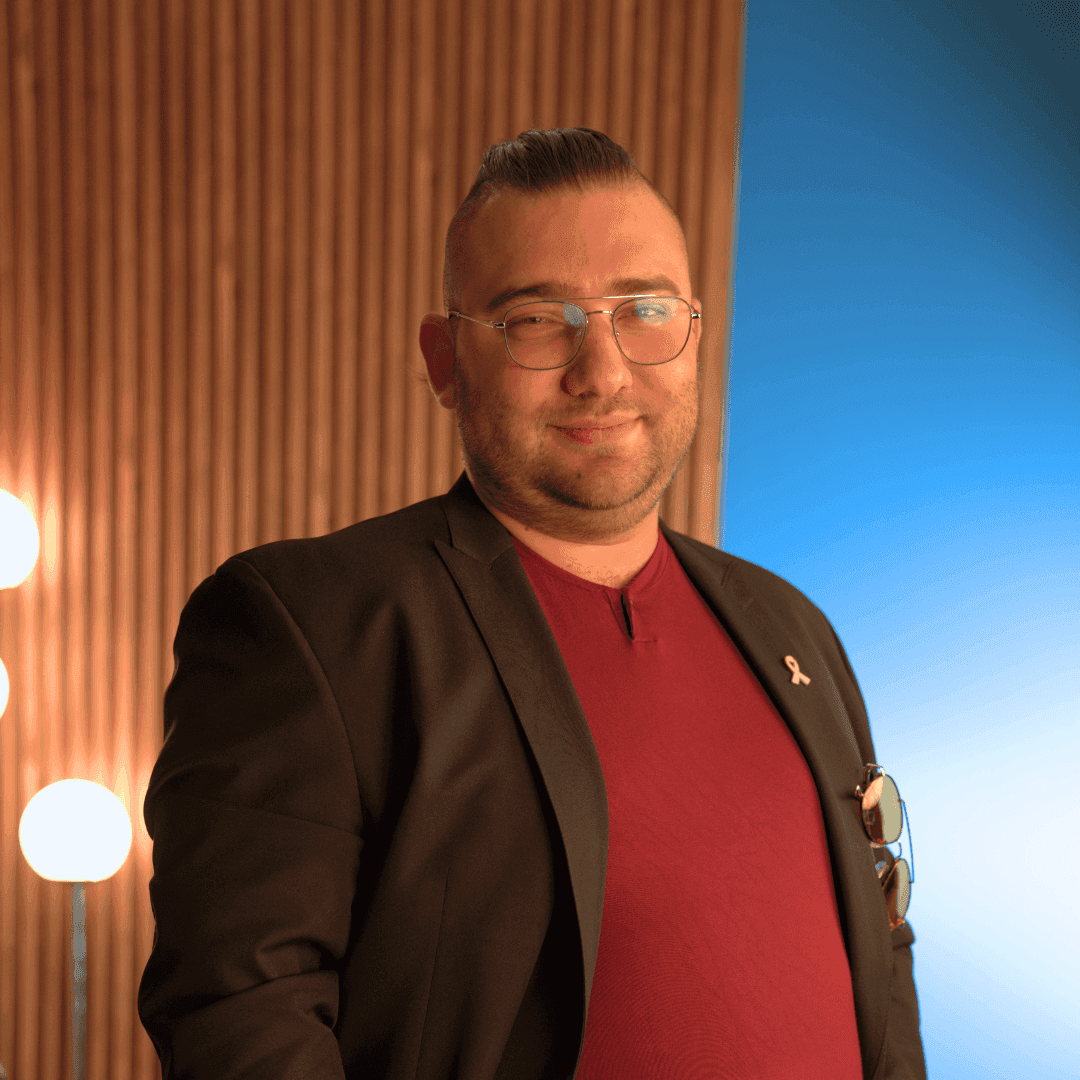
Alexander Slutsker
Business consultant, entrepreneur and founder of Mobius Business Solutions
- ✓Business projects of his own since an early age, and work with entrepreneurs, business owners and executives in Israel and abroad
- ✓MBA in Hi-Tech and Entrepreneurship
- ✓BBA in Marketing and Finance
A taste of the style
What Clients Say
From different fields, at different stages of business
Dan Manto
Eclipse Capital
Real Estate Investment and Finance, USA
Arty McLabin
GameReady
Game Development Education and Outsourcing, International
Anna
Beautician
After I finished a cosmetology course at a leading company, I was confused. I didn't know how to open a business, what to sell from home, or how to bring in clients. Since I reached out to Mobius, everything has changed. We built an organized plan with clear steps and no unnecessary risks. Today I see results, and I'm growing and developing every month.
Mark
Massage therapist, Gan Yavne
When I finished a massage course, I imagined a different world. I found out it's a hard field, and financial stability isn't easy to find. When I came to Mobius, something changed. We started an organized process and built a business plan. Without Mobius? I probably would have given up. Today I believe in myself and in my own path.
Want a lecture from this topic at your organization?
Send a message with the date, the audience and the lecture you are interested in.
Frequently asked questions
Part of the audience is experienced and part is new. Will it work?
Yes. I set the depth in advance on the intro call, I match the examples to your field, and the opening assumes no prior knowledge. Questions from the audience leave room for the experienced too.
What is the difference between a lecture and a workshop?
A lecture delivers insights, a thinking framework and examples to a large group. A workshop adds practice, discussion and work on your own cases in a smaller group. They combine well: a lecture for everyone and a follow-up workshop for a core team.
Can the lecture be delivered online?
Yes. Every lecture is offered both on site and online, with the same content. We choose the format together on the intro call.
Which languages are the lectures given in?
Hebrew, Russian or English, in the language your audience speaks.
How do I book a lecture?
Write to me on WhatsApp or through the contact form: who the audience is, which topic and when. Then we set up a short intro call, where I match the depth and the examples to your audience.
Not ready to talk yet? Get a feel for my content in the meantime.