Personal and Family Finance Consulting
Order in the household's money, and a plan you can keep.
Personal and family finance consulting helps families and individuals put the household's money in order: where it really goes, where it leaks, how big a reserve you need, and a budget you can keep even when the income changes from month to month.
+972 055-248-6151. Better on WhatsApp: I am in meetings most of the day and answer as soon as I am free. Other ways to reach me
We can talk in English, Hebrew or Russian.
Does This Sound Familiar?
The money runs out before the month does, and I'm not sure where it goes.
My income changes from month to month, and I have no way to plan around it.
We earn reasonably well, and still we don't manage to save.
We have loans and payments, and I don't know which to deal with first.
Sound familiar? The first conversation is free.
Book a Free CallWhat Clients Say
From different fields, at different stages of business
Dan Manto
Eclipse Capital
Real Estate Investment and Finance, USA
Arty McLabin
GameReady
Game Development Education and Outsourcing, International
Anna
Beautician
After I finished a cosmetology course at a leading company, I was confused. I didn't know how to open a business, what to sell from home, or how to bring in clients. Since I reached out to Mobius, everything has changed. We built an organized plan with clear steps and no unnecessary risks. Today I see results, and I'm growing and developing every month.
Mark
Massage therapist, Gan Yavne
When I finished a massage course, I imagined a different world. I found out it's a hard field, and financial stability isn't easy to find. When I came to Mobius, something changed. We started an organized process and built a business plan. Without Mobius? I probably would have given up. Today I believe in myself and in my own path.
What you get
A clear picture of the month
What has come in, what still has to go out and what is free to spend, visible at any point in the month.
Decisions by rules, not by the balance
Money decisions, big and small, made by simple rules you set in advance, not by how the account looks on the day.
Numbers you read yourself
You learn to read your own statements, so decisions about money stop feeling like guesswork.
Along the way you get the supporting and guiding materials the work needs, with clear instructions.
Simplified illustration
A household budget, simplified
Money coming in
Fixed expenses
Changing expenses
Saving
What is left
Money comes in, and the fixed expenses go out first, such as rent or a loan repayment, then the changing expenses, such as food and fuel, and then the saving you set aside. What is left shows how much room the month still has.
Simplified. A real household budget also carries the yearly payments, the one off expenses and the months when the income changes.
mobiusbiz.co.il
I have worked with
- Google for Startups
- House of Business, Sderot Municipality
- Microsoft Reactor
- GameReady
- Eclipse Capital
- SderoTech
- IUCEL
- Resilience & Health Innovation Hub
- International Resilience Institute of Sderot


- Google for Startups
- House of Business, Sderot Municipality
- Microsoft Reactor
- GameReady
- Eclipse Capital
- SderoTech
- IUCEL
- Resilience & Health Innovation Hub
- International Resilience Institute of Sderot
What the work can include
You do not need all of it. In the first conversation we choose together the parts your household needs.
- We go through the bank and credit card statements together, fixed and changing expenses apart, and find where the money leaks.
- I build with you a household budget the family actually uses, personal budget management built on what you really spend, not on an ideal.
- We set a reserve target: how much the household needs aside for a weak month or a surprise, and how to get there.
- For income that changes every month, I set with you a simple plan for a good month and a weak one: basic expenses, tax set aside if you are self employed, the reserve and flexible spending.
- When there are loans and payments, we decide together which one to deal with first.
- For the self employed and business owners, I put home money and business money in one picture: what the business has to bring home and what the household has to protect.
- When pensions, savings or investing come up, I bring in an investment or pension adviser from my side, and you arrive with the numbers clear.
- I work with any household: a single person, a couple or a family, salaried or self employed.
How the work goes
A free first conversation
We talk, see whether my work fits what your household needs, and I suggest the kind of work that suits you.
Where the money really goes
We go through the bank and credit card statements together and see what is fixed, what changes and where money leaks.
A plan the household can keep
Together we set the budget, the reserve target and simple rules for a good month and a weak one.
The ongoing work
We meet as often as you need. Between meetings you can send me a short question on WhatsApp, and I reply as soon as I can.
Want to see how these steps would look for you? That is what the first conversation is for.
Book a Free Call9+ years of experience in business consulting
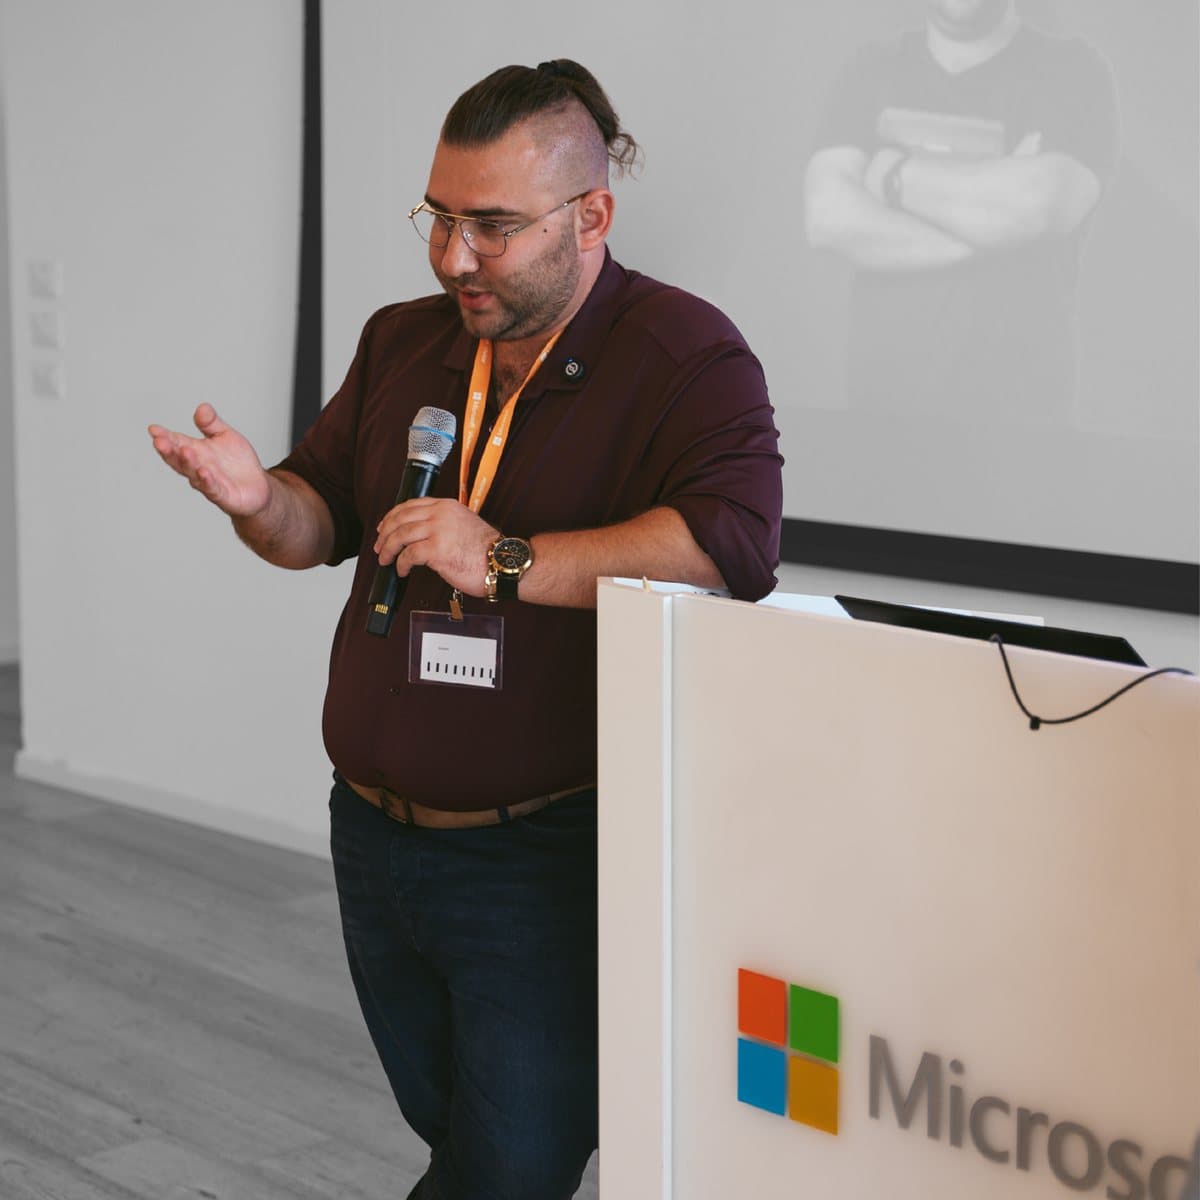
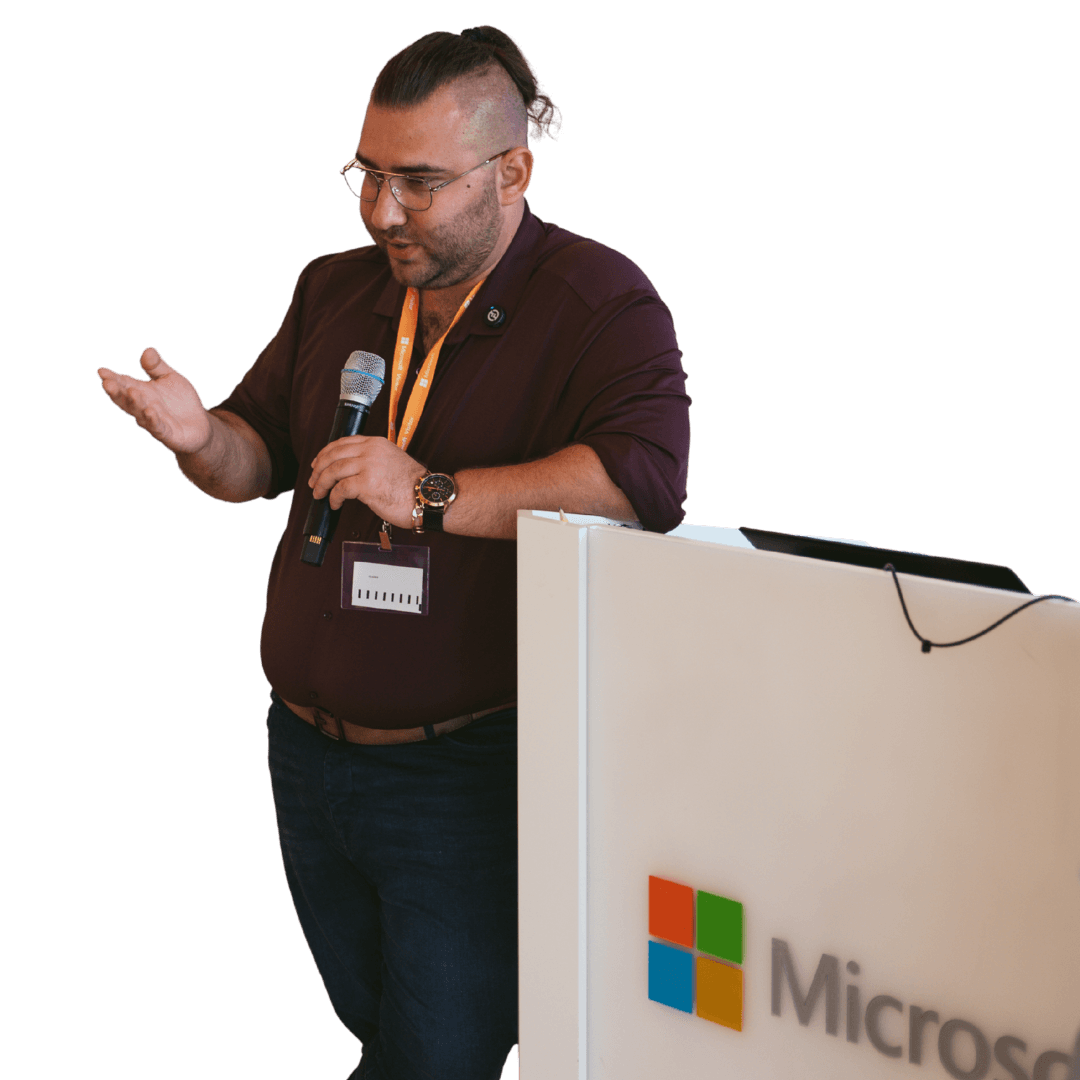
Speaking at Microsoft
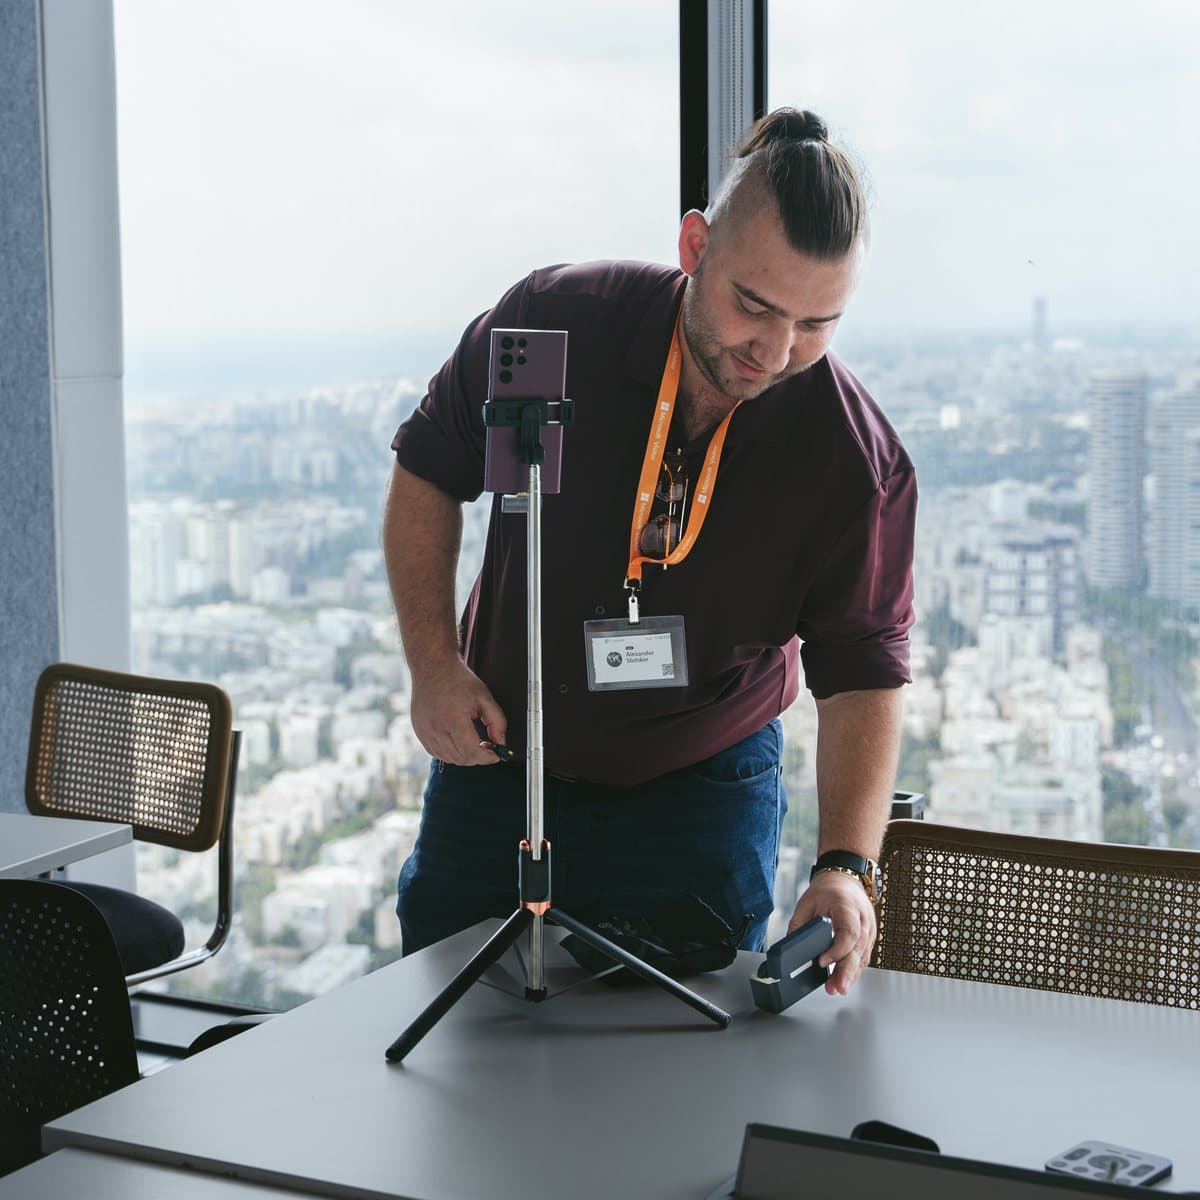
Meeting with international teams, as part of work with a startup
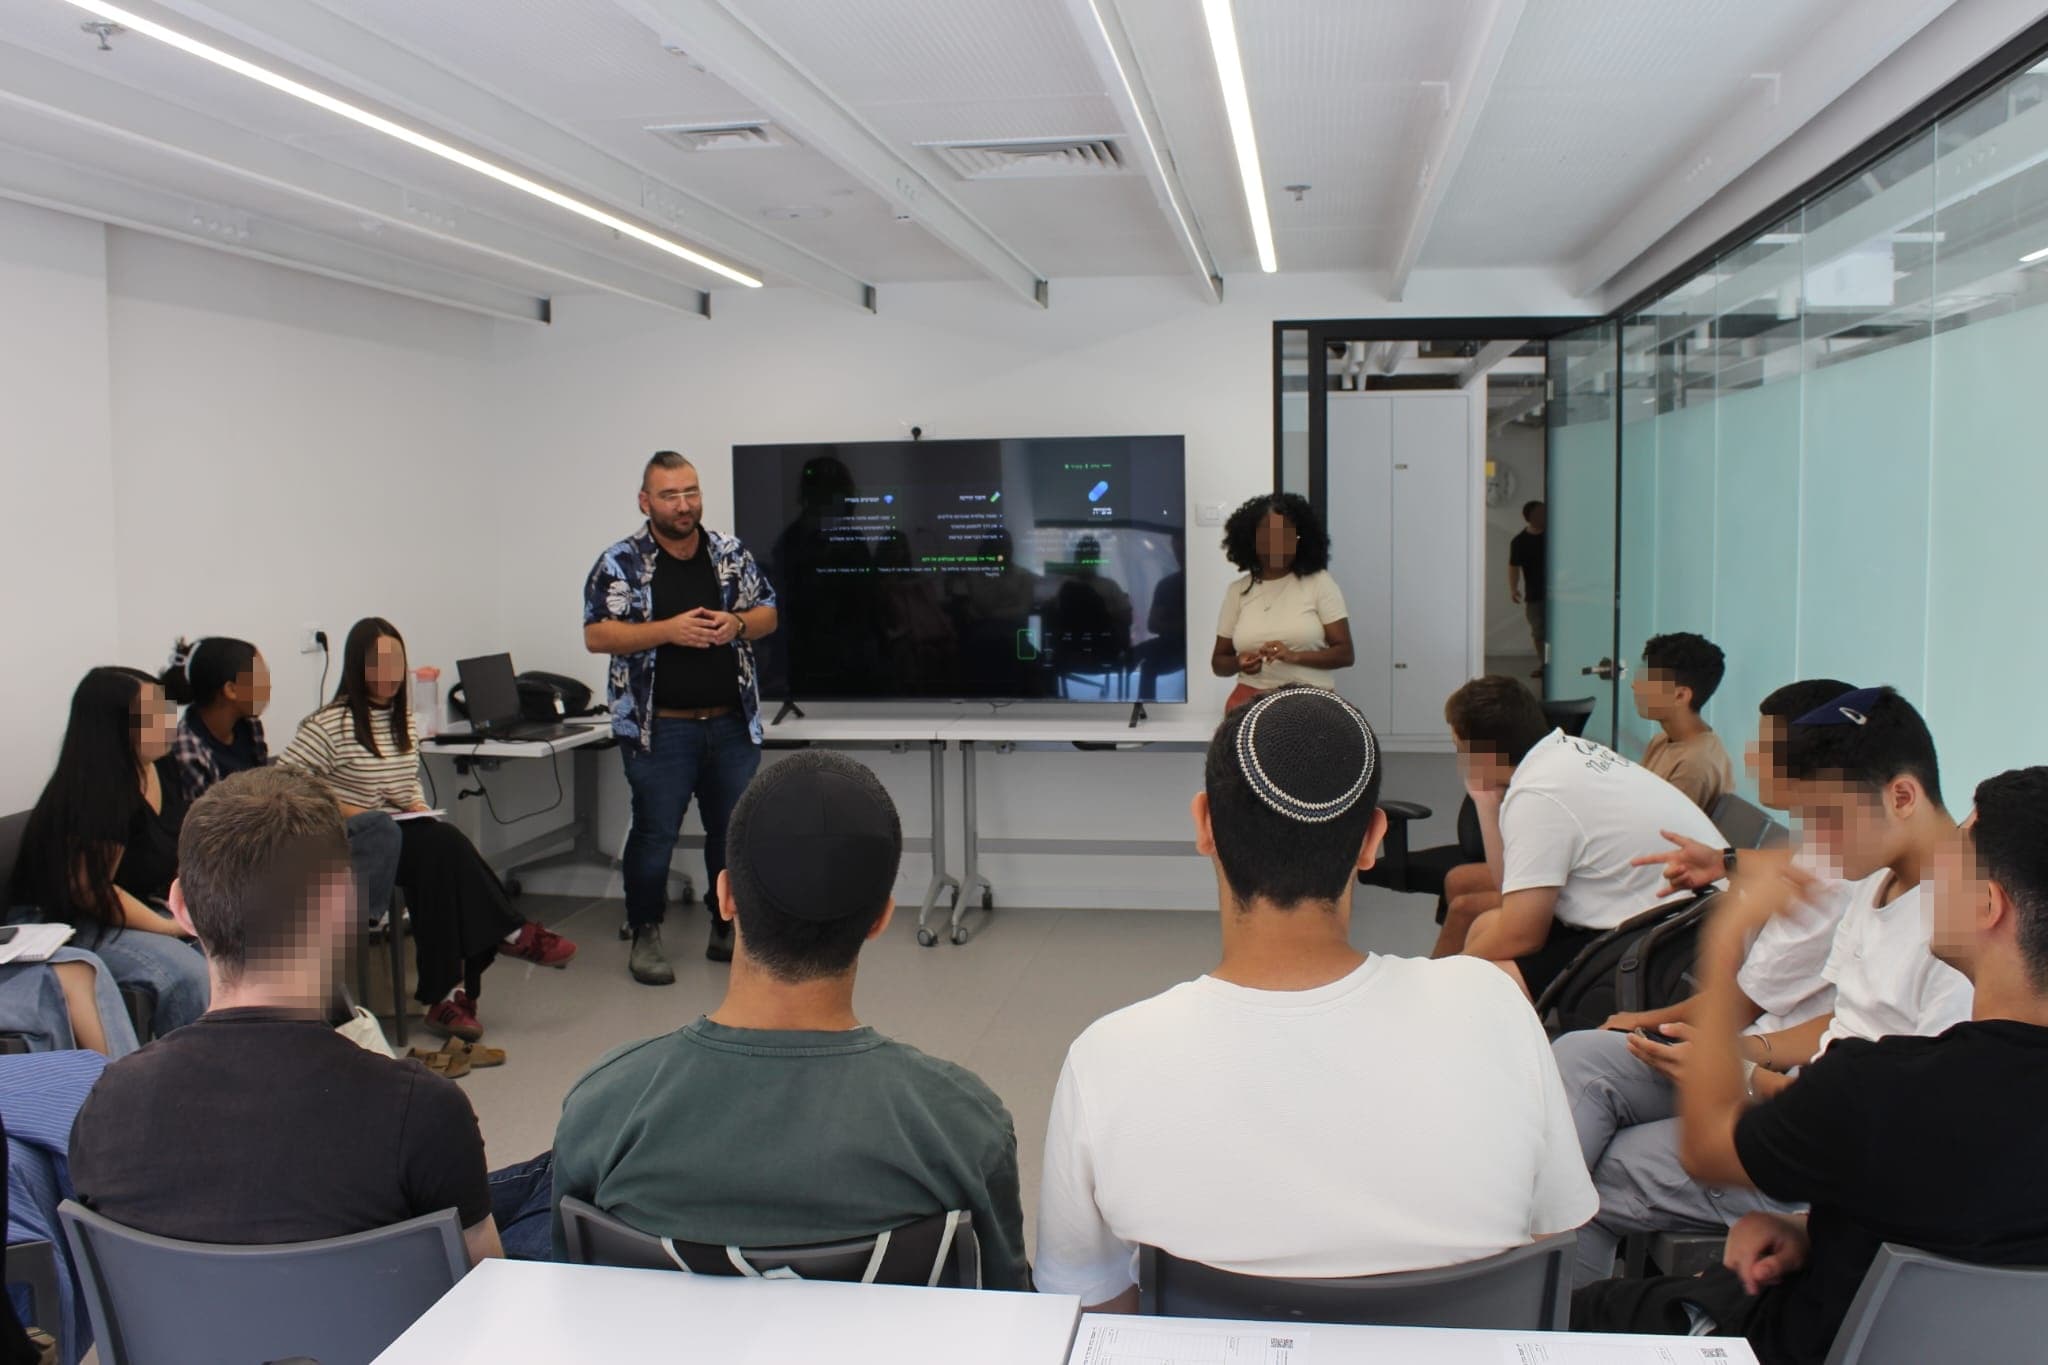
Teenovation, Meital centre Sderot
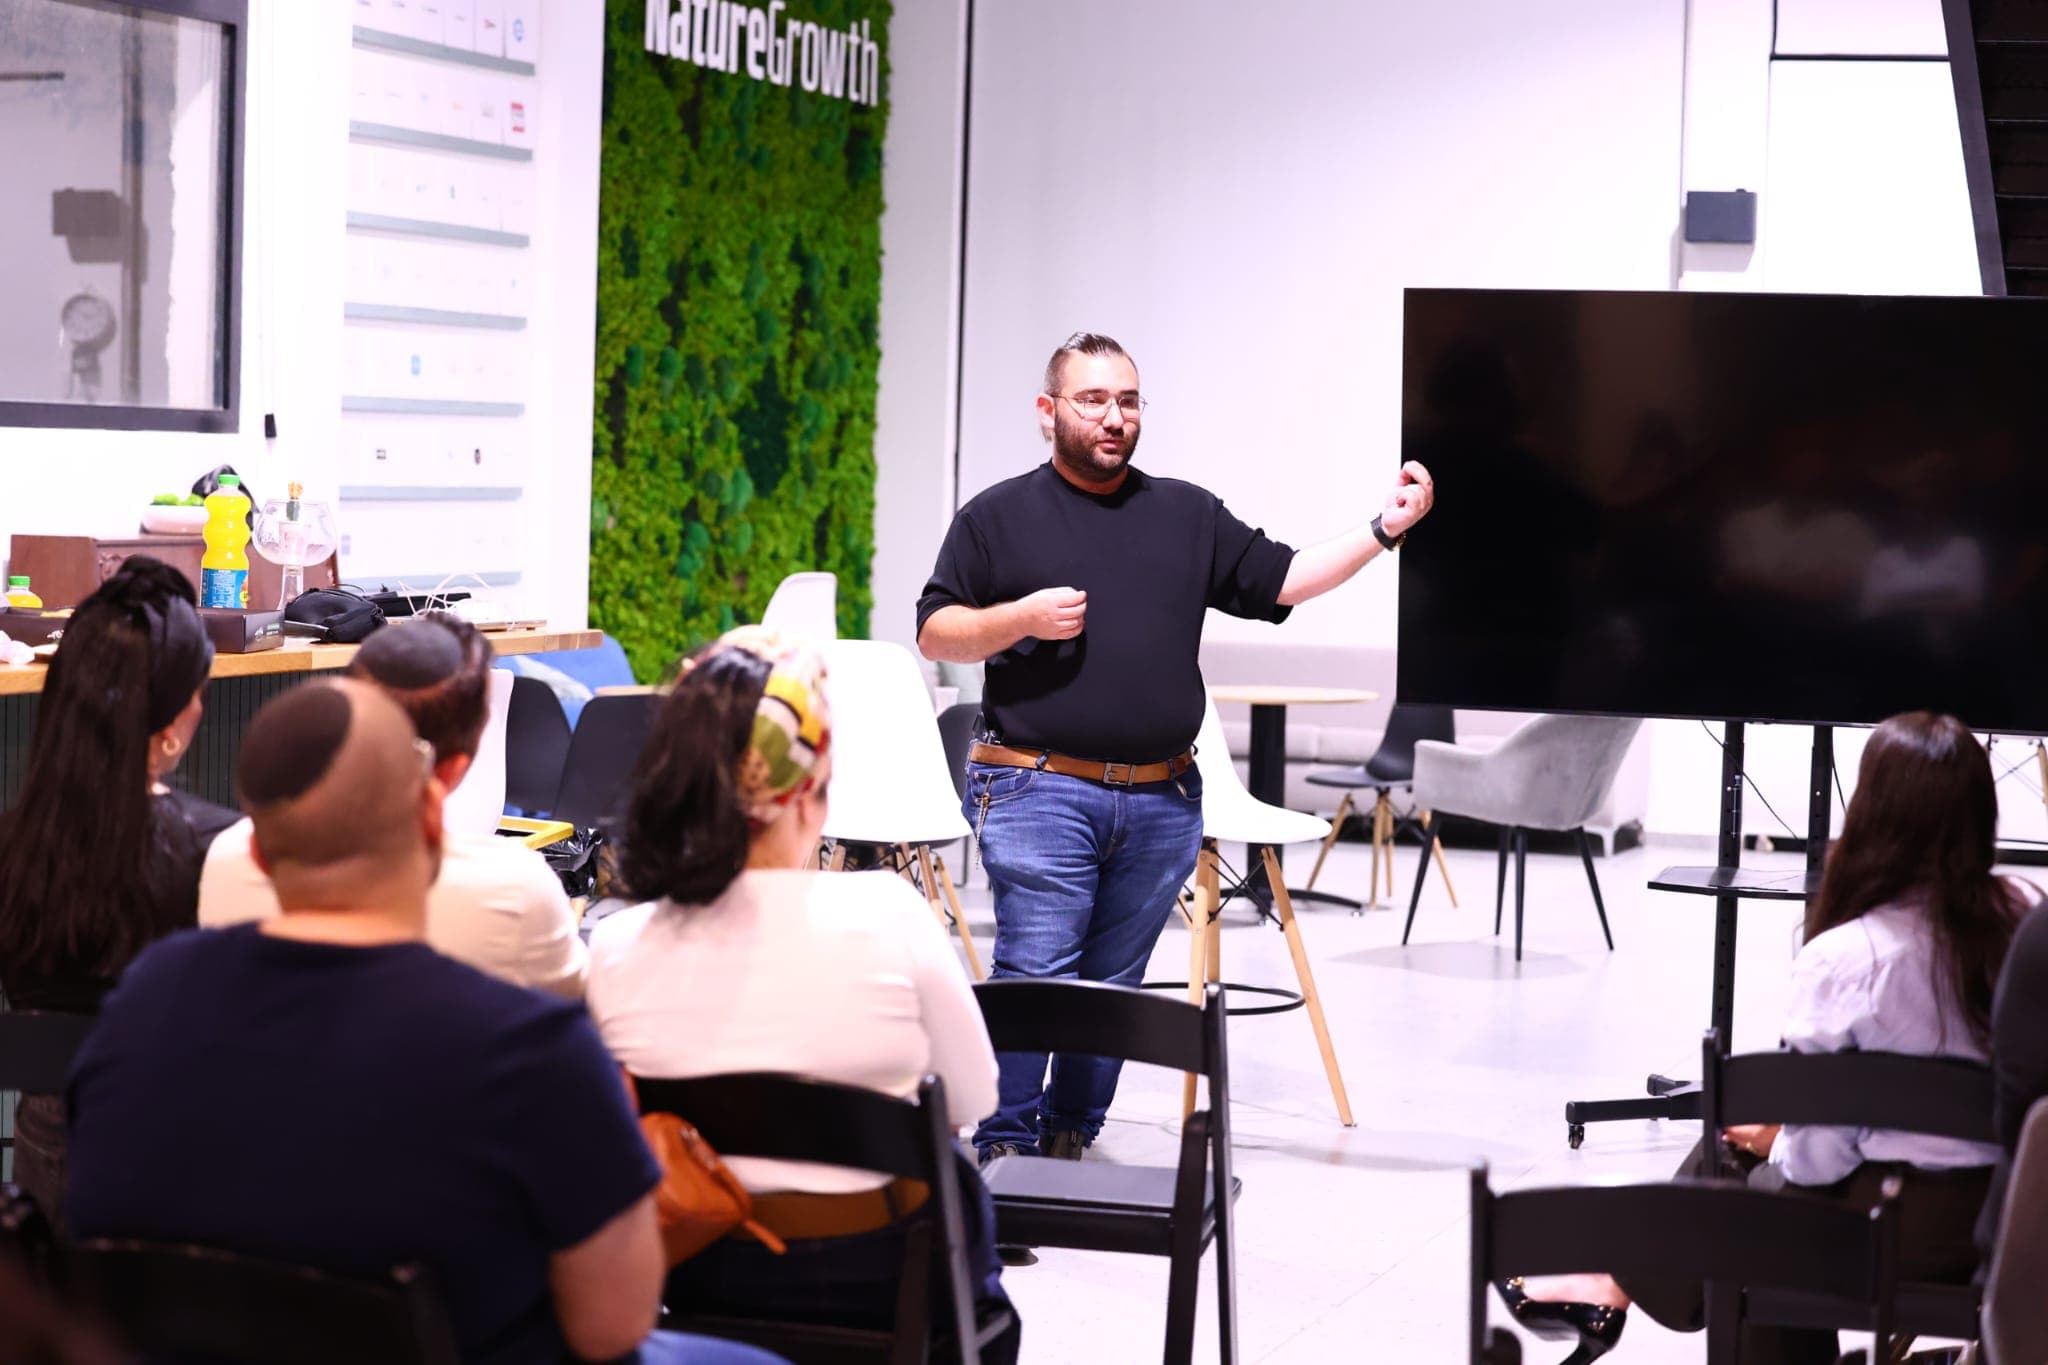
Entrepreneurs session, Sderot
Who does what
What I do
- Go through the numbers with you and find the leaks
- Build the budget and the rules with you
- Stay with you while the new habits settle in
What you do
- Bring the statements and the list of payments
- Decide what changes, the decisions stay yours
- Keep to the budget day to day
Personal recommendations on securities, pension or insurance are given only by licensed professionals, so that part stays with the adviser I bring in.
What to bring to the first conversation
Bring what you already have, even if it is incomplete. We can start without it too.
- Bank and credit card statements for the last few months
- A list of loans and fixed payments
- Pay slips or other records of income
Whatever you show me about your money stays between us, exactly as it does for every other client of mine.
Who it fits
- A family that earns reasonably well and still does not manage to save.
- A self employed person whose income changes every month.
- A single person or a couple before a big step, such as a loan or a move.
When is it better to start elsewhere?
If the money that worries you is the business's money, its prices or its profit.
In that case, start here: Financial Consulting for Businesses
And the paperwork, for anyone who wants to see that too.
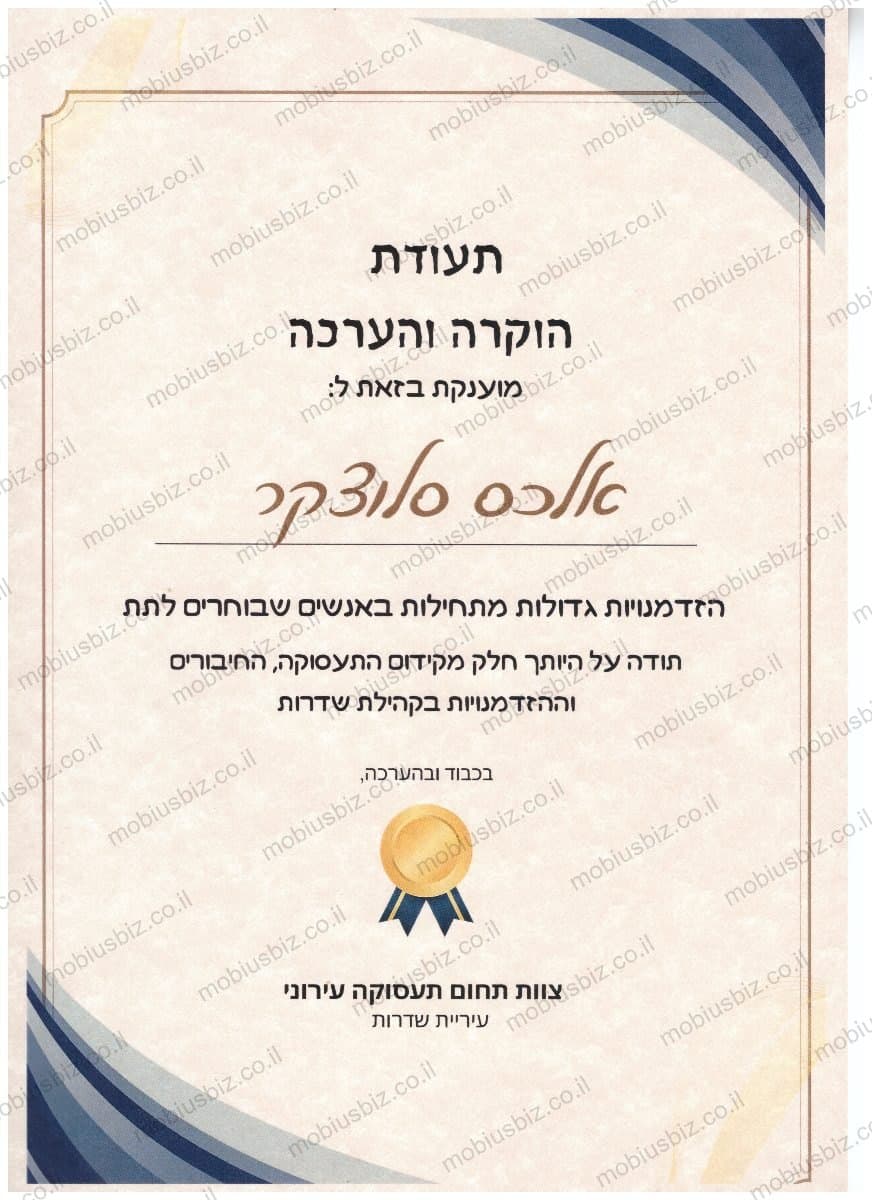
Certificate of appreciation, Sderot municipality
Certificate of honor, Teenovation 2026
Directors and officeholders course, SRI Campus
Acceleration program, MaofTech South
Business consultants course
Adaptive project management, INT college
You work directly with me, and I stay your point of contact throughout the work.
- How does it start?
- With a free first conversation of 15 to 30 minutes, by phone or by video. In it we name what bothers you about the household's money and shape the work around it. The answer is not handed over in that conversation, it comes out of the work that follows.
- How much of our time will it take?
- A meeting of about an hour, as often as needed, and a little more at the start while I learn how the household runs. The rest is living by the plan, and that happens in your daily life anyway.
- Do our papers have to be in order first?
- No. Statements and records help, but they are not a condition for starting. We begin from what you have and put the rest in order along the way.
- Is this for us?
- It is for any household, a single person or a family, salaried or self employed. For business owners, the home money and the business money are looked at in one picture.
Frequently asked questions
Can you help if my income changes every month?
Yes. Income that changes needs a different system than a fixed salary. I split the money into four pots: basic expenses that must be covered every month, tax set aside before it gets spent, a reserve for the weak months, and flexible spending that moves with the income. Decisions are made from a realistic monthly average over a longer stretch, not from the best month or the panic of a weak one. The point is steady decisions through the whole year, with clear rules for what to do with a surplus.
Do you give investment advice, or focus on the budget?
The budget. My work is the household's expenses: finding where money leaks, putting it in order and building a plan the family can keep. That order is also what decides whether any savings or investment plan survives real life. So when you meet the investment or pension adviser I bring in, you arrive with a clear picture: what money you will need soon, what can be put away for years, and how much up and down you can live with.
Should personal and business money be looked at together?
For the self employed and business owners, almost always yes. Home money and business money are tied together through salary, withdrawals, taxes, business debt and family commitments. Looked at separately, a real risk can hide: an owner can look profitable in the business and exposed at home, or the other way round. I build one picture that shows what the business has to bring home reliably, what the household has to protect, and where personal spending quietly pushes toward risky business decisions.
Is this only for business owners?
No. Personal financial planning fits any household, a single person or a family, salaried or self employed. The work is the same: see where the money goes, close the leaks and build a budget the household keeps.
How is this different from business finance consulting?
Here the subject is the home: the family budget, the reserve, the loans. Business finance consulting deals with the business's money: the money coming in and going out, the prices and the profit. For the self employed the two often meet, and then we look at both together.
Do I need to know anything about finance first?
No. I explain every term in plain words the first time it comes up. Part of the work is that you learn to read your own numbers, so decisions about money stop feeling like guesswork.
Related services
- Financial Consulting for BusinessesWhen the question is the business's money, not the home's.
- Separate Personal and Business Money Before the Bank Balance LiesFor the self employed: why home money and business money are kept apart first.
New to consulting? Start with the map of what business consultants do
Ready to Get Started?
Book a Free Call+972 055-248-6151. Other ways to reach me
We can talk in English, Hebrew or Russian.