Startups vs Stocks: The Real Investing Logic
A careful comparison of public stocks, bonds, funds, private startup exposure, liquidity, diversification, and founder lessons.
Stocks, bonds, public funds, private equity, and direct startup investments are not interchangeable. They solve different problems, carry different risks, and give investors very different levels of liquidity, information, control, and upside.
This article is educational, not personal investment advice. The point is to explain the logic so founders understand how investors think, and so readers do not compare a startup investment with a public stock as if they were the same object.
Public assets and startup investments solve different problems
Public-market investing usually gives easier access, more frequent pricing, more regulation, and more ways to diversify. Investors can often buy or sell public stocks and funds through a brokerage account, although prices can still fall sharply.
Startup investments are private. They are usually illiquid, harder to value, and exposed to business survival risk. The company may have limited operating history, limited disclosure, unclear market proof, and a long path before any exit.
The mistake is to compare only the possible upside. You also have to compare the chance of loss, the time money may be locked, the quality of information, and whether the investor can tolerate uncertainty.
Stocks, bonds, and funds are easier to diversify
Investor.gov explains that asset allocation and diversification are connected to time horizon, risk tolerance, and spreading money across different investments. Public funds can help investors diversify across many companies or securities with one purchase.
Bonds are different from stocks because they represent lending to an issuer, while stocks represent ownership. Funds can hold baskets of assets. None of these are risk-free, but they usually give clearer pricing and easier diversification than direct startup exposure.
That does not make public markets automatically better. It means the comparison must be honest.
Startup investments are private, illiquid, and high risk
Private offerings can involve early-stage companies, limited information, restricted securities, illiquidity, and the possibility of losing the full investment. That matters because many startup investments cannot be exited on demand.
The investor may wait years for a sale, merger, secondary transaction, public offering, or another liquidity event. Or there may be no exit at all.
For founders, this explains why investors ask about market size, exit paths, follow-on capital, governance, reporting, and the cap table. The investor is not only buying today's story. They are accepting a long period of uncertainty.
Higher potential upside comes with higher loss risk
The logic of a startup investment is that the upside might be much larger than the initial investment. But that upside exists because the risk is also much higher. If the risk were low and the outcome obvious, the investment would not be priced like an early-stage bet.
This is why investors look for asymmetry. They ask whether a small check could become meaningful if the company wins, while also accepting that the investment could be lost. That is not a promise. It is the risk-return tradeoff.
This is also why founders must be careful with claims. A pitch that shows only upside and hides risk usually weakens trust. A pitch that explains the risk and the path to reducing it sounds more serious.
Diversification, time horizon, and risk tolerance
Startup exposure usually belongs in a discussion about diversification, time horizon, and risk tolerance. It should not be framed as a guaranteed shortcut to wealth.
Before considering a startup investment, a reader should understand:
- The investment may be illiquid for years.
- The company may need future rounds, causing dilution (a shrinking ownership percentage).
- The valuation may be uncertain.
- Information may be limited compared with public companies.
- Legal rights may matter as much as ownership percentage.
- A small company can fail even if the idea is good.
That is why anyone making real investment decisions should get qualified financial, legal, and tax guidance.
Questions to ask before considering a startup investment
A disciplined investor or angel should ask:
- What problem is the company solving, and for whom?
- What proof shows customers act?
- What is the market size and realistic first beachhead?
- How does the company acquire customers?
- What are the gross margin and delivery costs?
- How much cash is needed to reach the next milestone?
- What are the terms, rights, and future dilution risks?
- What could make the investment become illiquid or worthless?
These questions overlap with founder preparation for early-stage fundraising and the investor logic behind why investors back risky startups.
What founders can learn from this logic
Founders sometimes think investors only want excitement. In reality, investors want a risk they can understand.
The founder should be able to explain how big the business could become, the current evidence, the next milestone, the economics, the financing path, and the terms of ownership. If equity is part of the conversation, understand the basics in what equity means in business.
The best fundraising story does not say "this is safe." It says: "This is the risk, this is the potential, this is what we already know, and this is what the next money will prove."
Preparing that story before investor meetings is part of startup consulting and fundraising preparation.
If you want to prepare that story before investor conversations, talk it through with me.
The content on this blog is general information only and is not a recommendation to act. It is not business, legal, tax, or financial advice. Before making any decision, consult a qualified professional, such as an accountant, a lawyer, or a business advisor, about your specific situation.
Speaking at Microsoft
Meeting with international teams, as part of work with a startup
Teenovation, Meital centre Sderot
Entrepreneurs session, Sderot
I have worked with
- Google for Startups
- House of Business, Sderot Municipality
- Microsoft Reactor
- GameReady
- Eclipse Capital
- SderoTech
- IUCEL
- Resilience & Health Innovation Hub
- International Resilience Institute of Sderot


- Google for Startups
- House of Business, Sderot Municipality
- Microsoft Reactor
- GameReady
- Eclipse Capital
- SderoTech
- IUCEL
- Resilience & Health Innovation Hub
- International Resilience Institute of Sderot
What Clients Say
From different fields, at different stages of business
Dan Manto
Eclipse Capital
Real Estate Investment and Finance, USA
Arty McLabin
GameReady
Game Development Education and Outsourcing, International
Anna
Beautician
After I finished a cosmetology course at a leading company, I was confused. I didn't know how to open a business, what to sell from home, or how to bring in clients. Since I reached out to Mobius, everything has changed. We built an organized plan with clear steps and no unnecessary risks. Today I see results, and I'm growing and developing every month.
Mark
Massage therapist, Gan Yavne
When I finished a massage course, I imagined a different world. I found out it's a hard field, and financial stability isn't easy to find. When I came to Mobius, something changed. We started an organized process and built a business plan. Without Mobius? I probably would have given up. Today I believe in myself and in my own path.
And the paperwork, for anyone who wants to see that too.
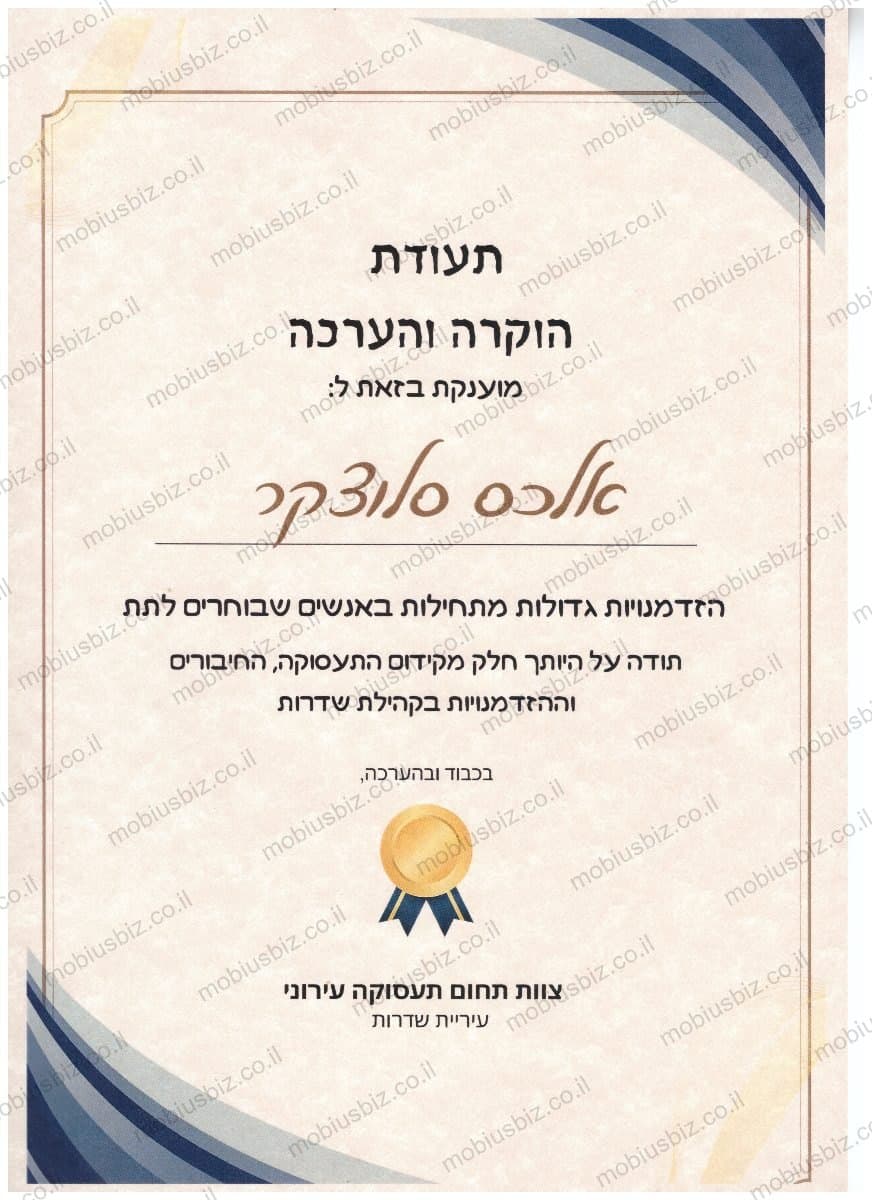
Certificate of appreciation, Sderot municipality
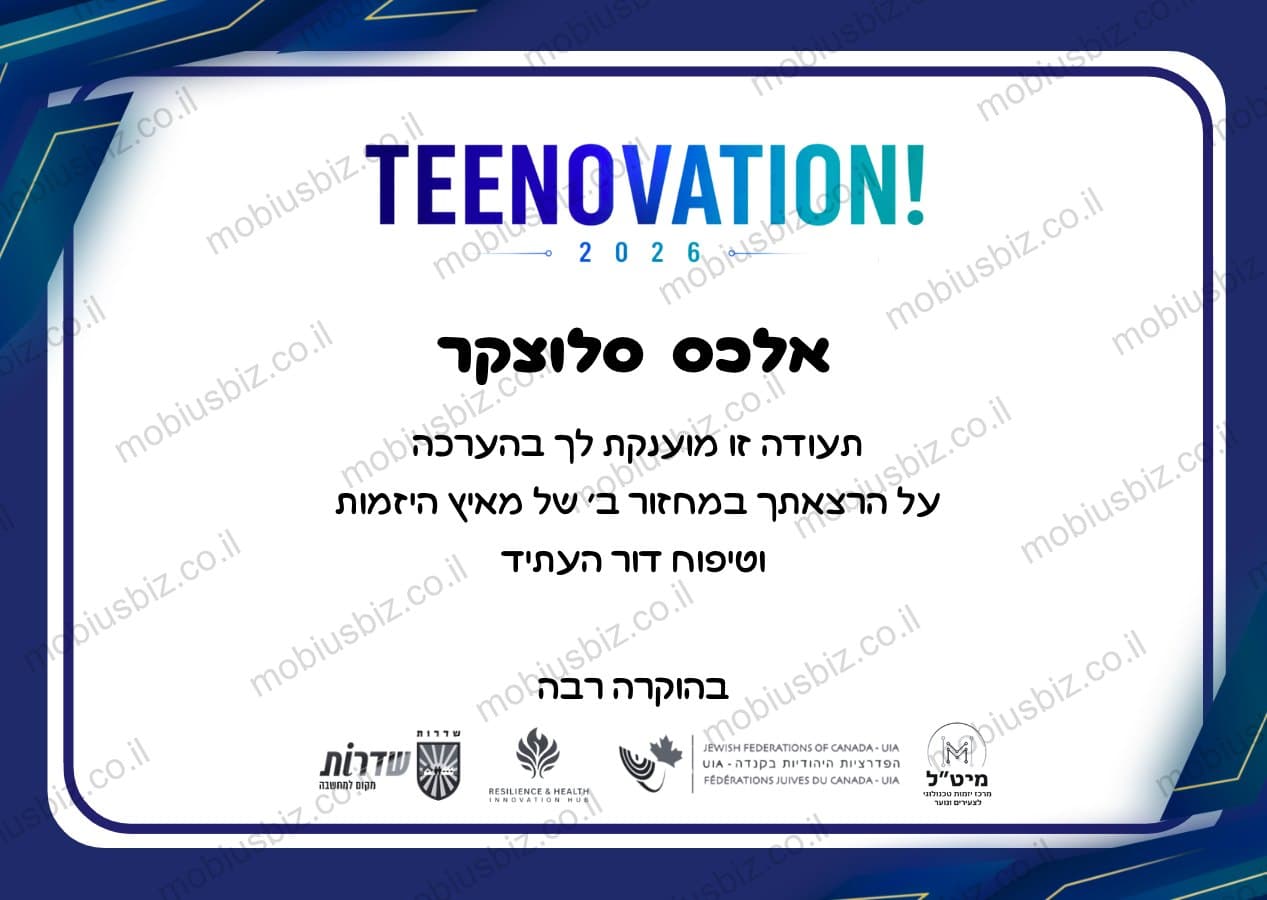
Certificate of honor, Teenovation 2026
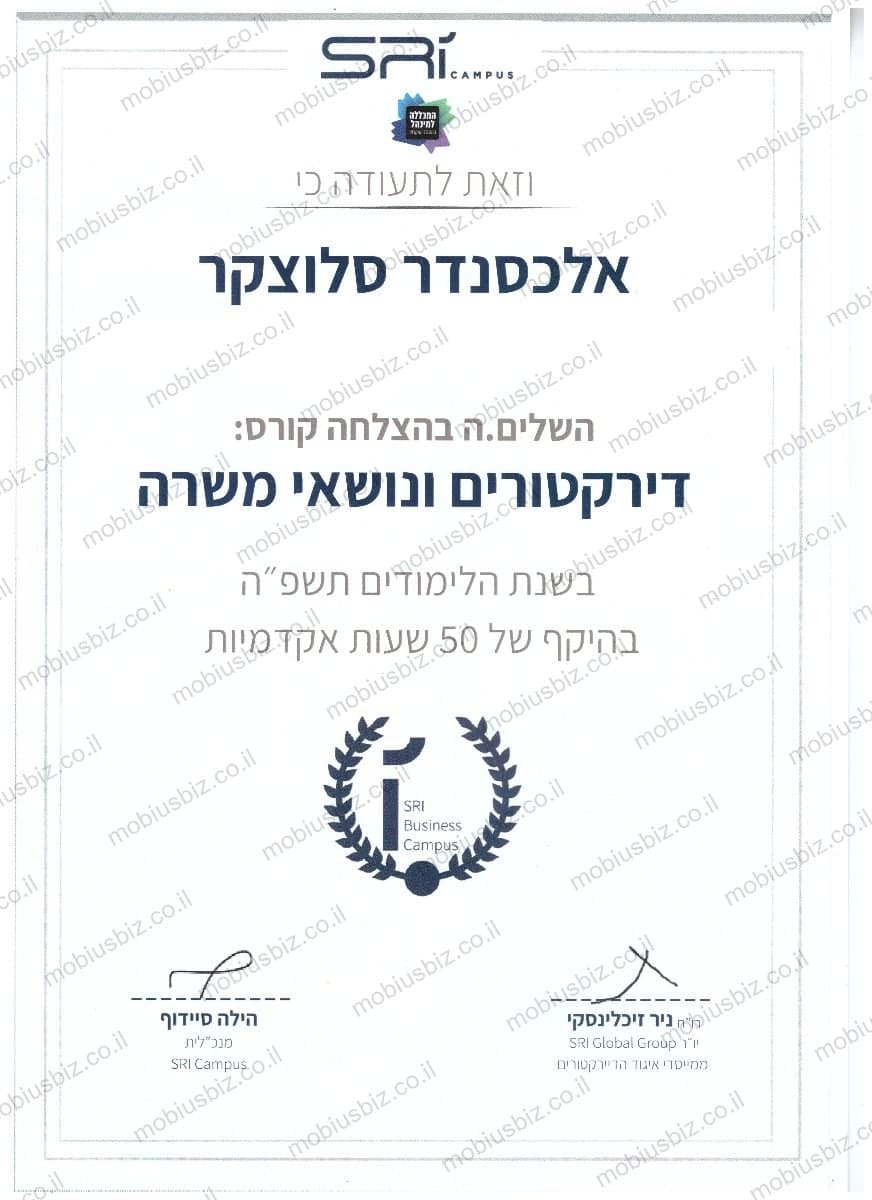
Directors and officeholders course, SRI Campus
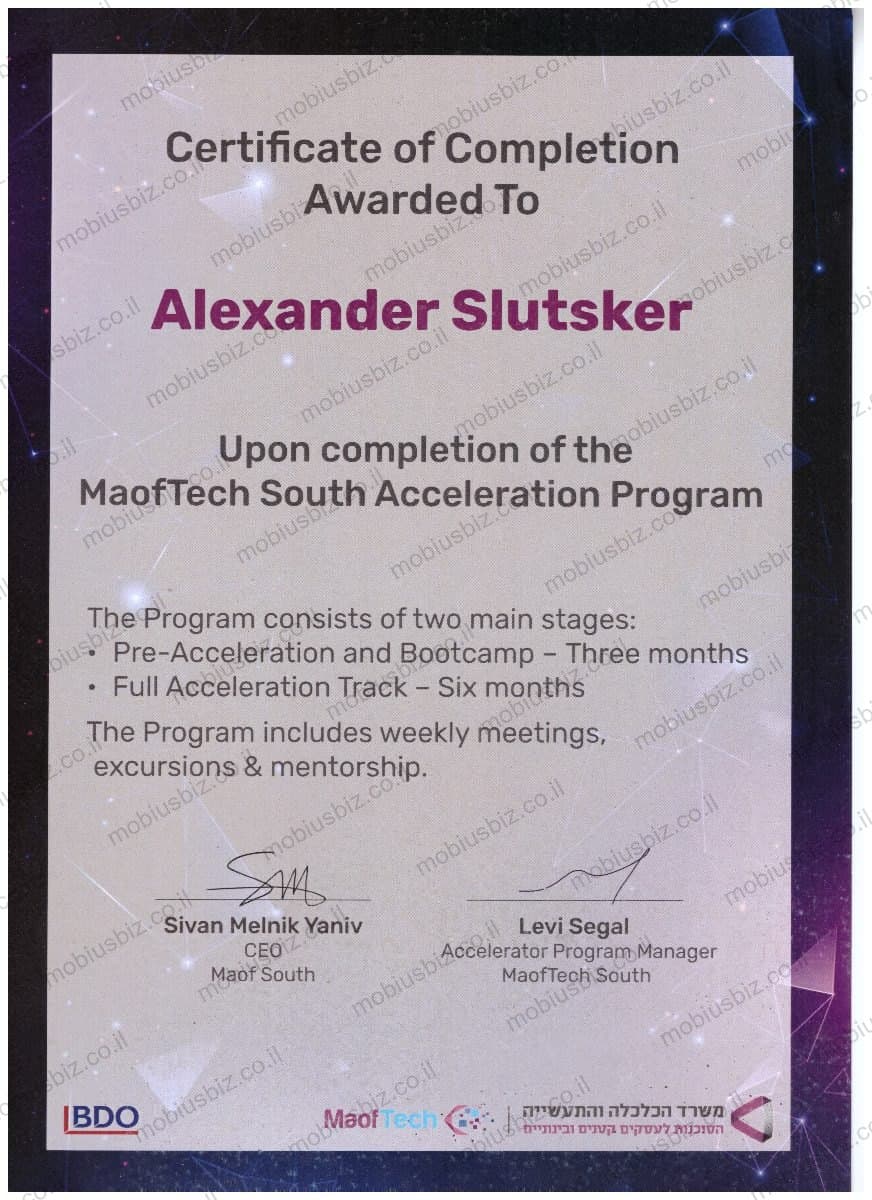
Acceleration program, MaofTech South
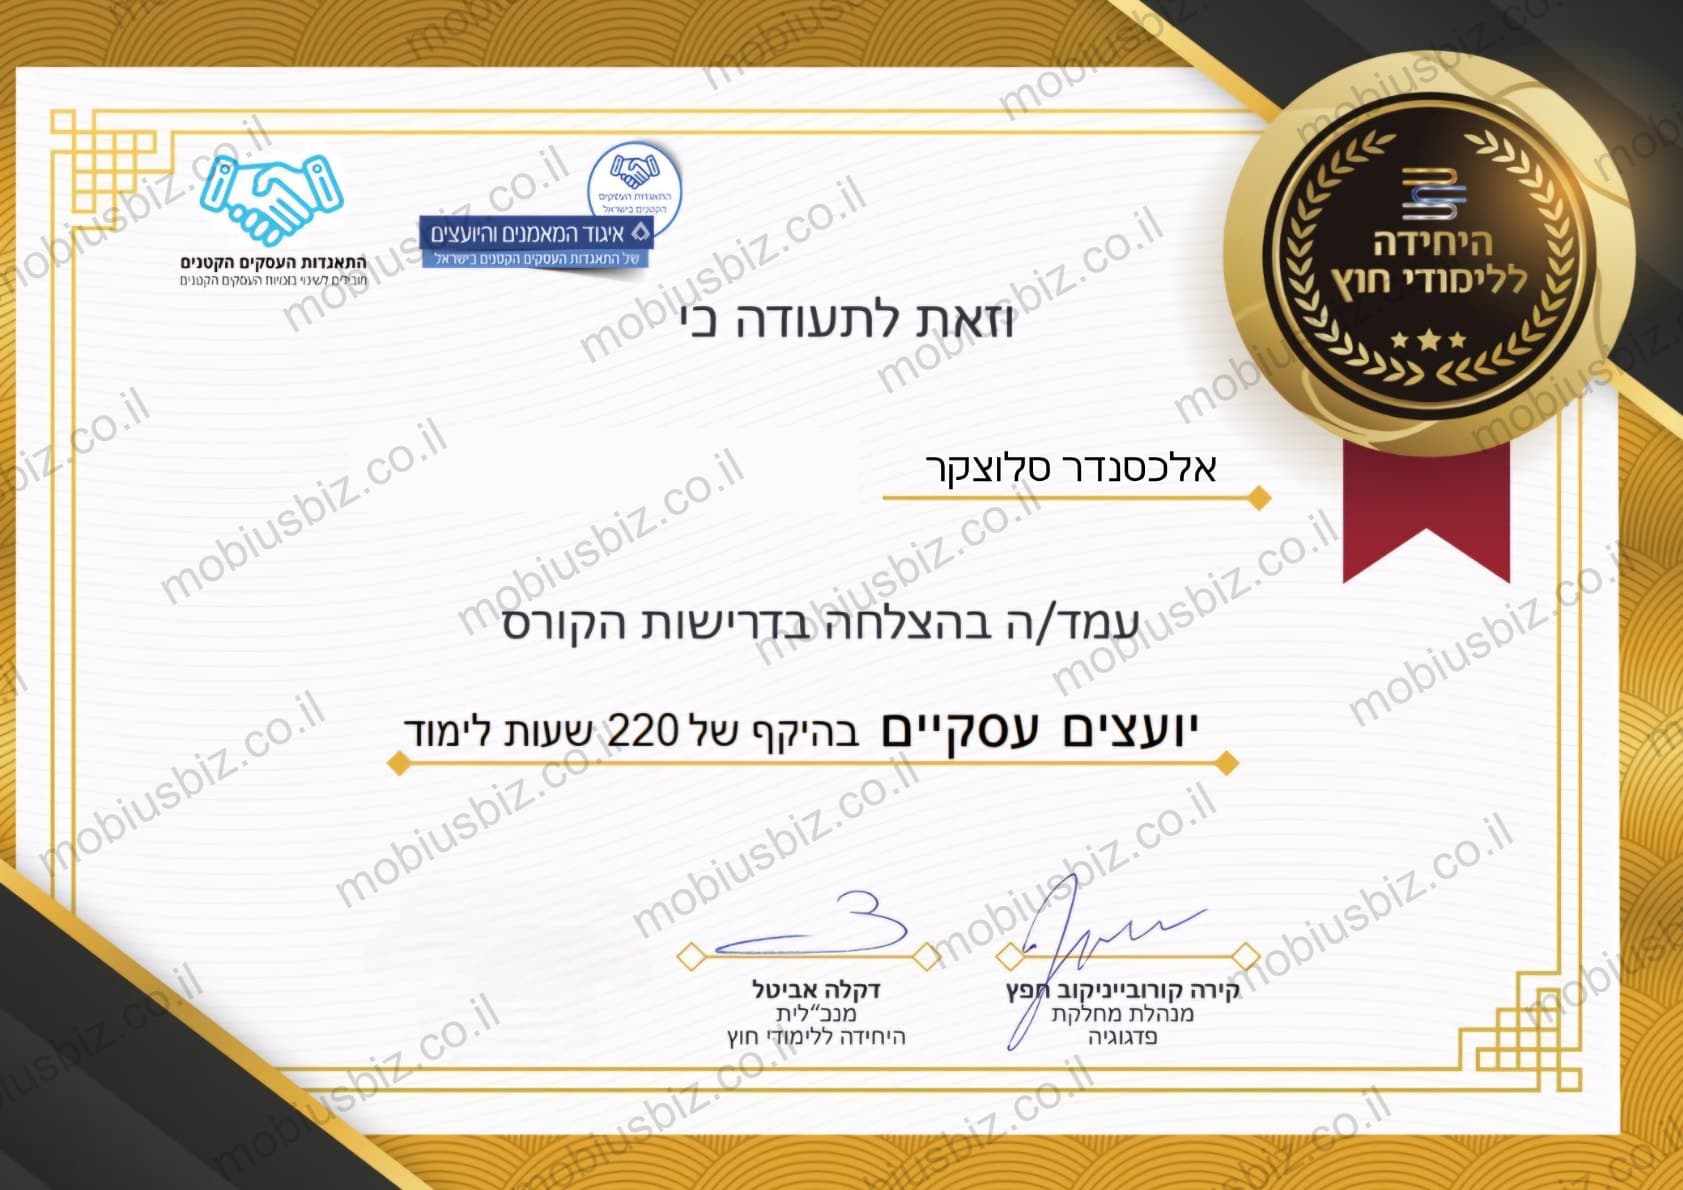
Business consultants course
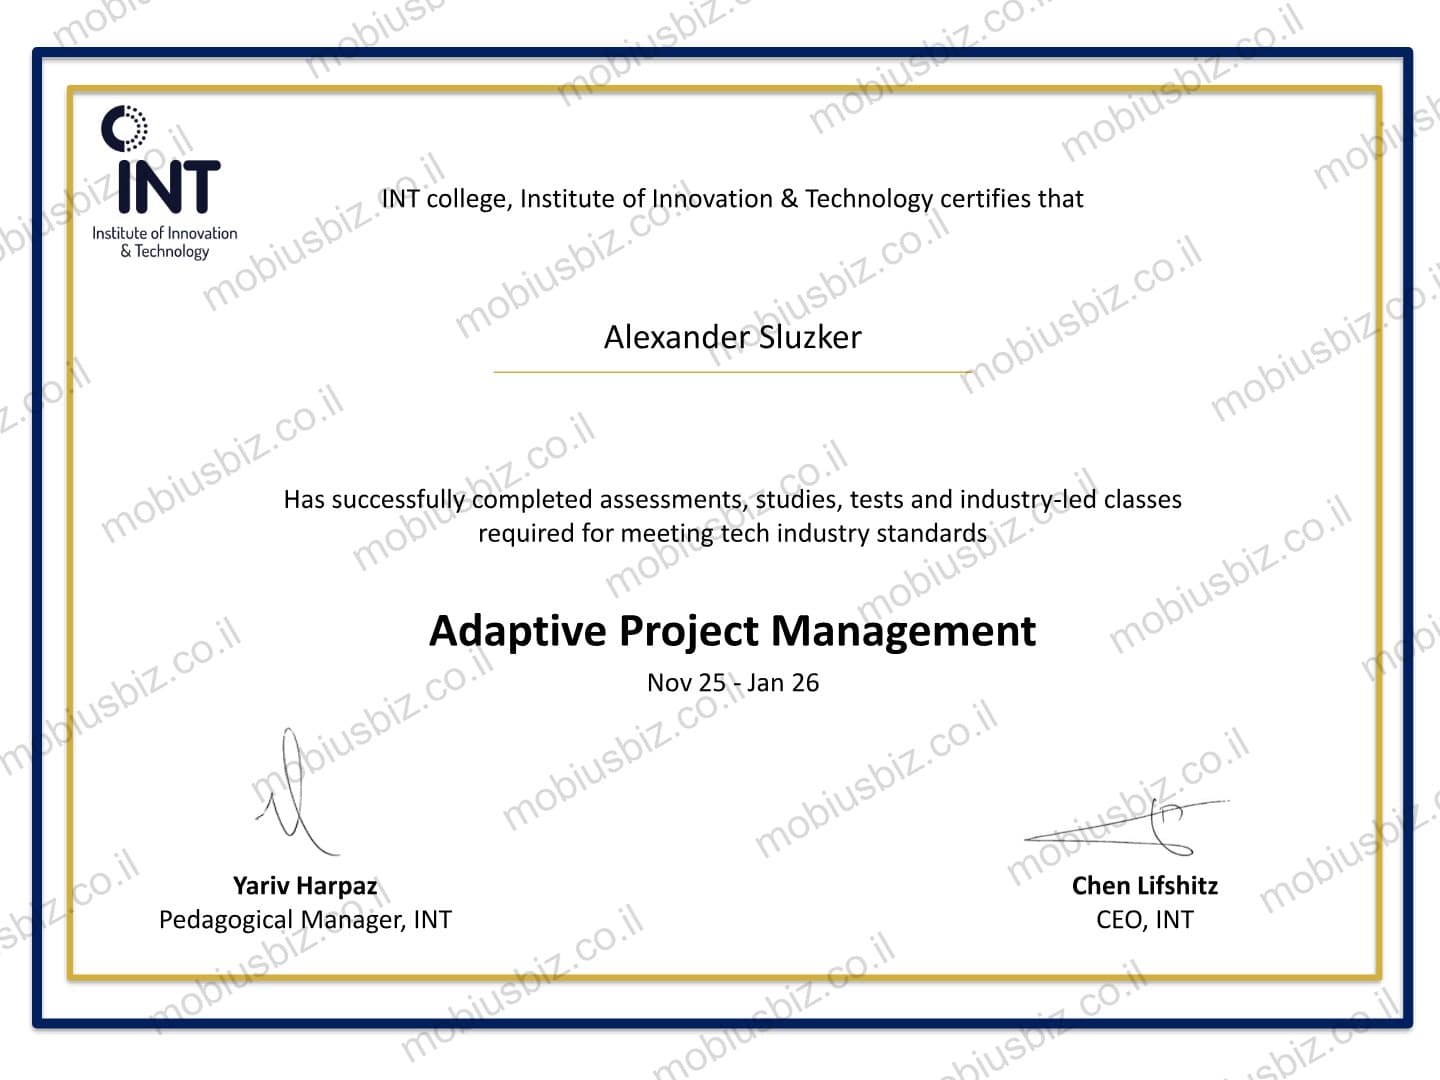
Adaptive project management, INT college
Business, Marketing, Operations & Financial Consultant
Mobius
Alexander Slutsker
9+Years of experience in business consulting
I help entrepreneurs, self-employed people, small businesses and startups understand their own numbers, choose what to do first and grow from there.
Book a Free Call+972 055-248-6151. Better on WhatsApp: I am in meetings most of the day and answer as soon as I am free. Other ways to reach me
We can talk in English, Hebrew or Russian.